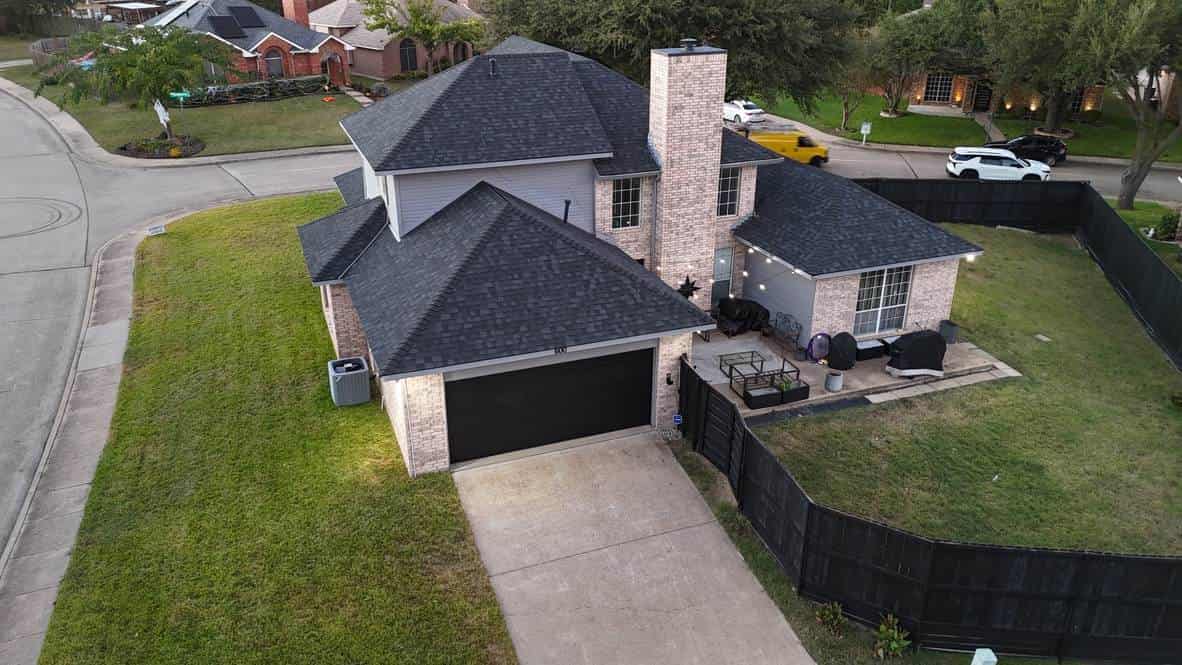
Aerial view of a home with a new charcoal shingle roof

Insurance help

How roof insurance claims work in Texas.

Storm claims can be confusing. This guide explains the process so you can make informed decisions with your insurance company. We're roofers, not adjusters, so this is general information, not legal or coverage advice.

  • Plain-English steps
  • Know your policy
  • Red flags to avoid
(214) 998-1834

Get your free inspection

We call within 24 hours to pick a time.

No cost, no obligation. We'll only use your number to schedule your inspection.

1. Know your policy

Ask your insurance company for a copy of your declarations page. It lists your coverages, your deductible (often a percentage of your home's insured value for wind and hail), and any exclusions or endorsements that affect your roof.

2. Document the damage

Write down the date of the storm. Take photos of damage you can safely see from the ground: dented gutters, damaged siding, broken screens. A professional inspection can document what's on the roof itself.

3. File the claim

You file the claim directly with your insurance company, usually by phone, app or online. Many policies have deadlines for reporting storm damage, so check yours. Keep your claim number and notes of every conversation.

4. The adjuster inspection

Your insurance company sends an adjuster to inspect the damage. You can have your roofer present to point out what they documented. The adjuster works for the insurance company and determines what the policy covers.

5. Understand the estimate

If the claim is approved, you'll receive an estimate. Two terms matter:

  • Actual cash value (ACV): the value of your roof after depreciation for its age
  • Replacement cost value (RCV): the cost to replace it new. Some policies pay ACV first and release the rest (recoverable depreciation) after the work is complete

If you disagree with the decision

Ask your insurance company to explain the decision in writing and whether a reinspection is possible. Many policies include an appraisal provision for disputes over the amount of loss. That's a right you, the policyholder, can use. For help with a disputed claim, talk to a licensed public adjuster or an attorney, or contact the Texas Department of Insurance.

Red flags

Protect yourself from bad actors after a storm:

  • Anyone who offers to waive, cover or rebate your deductible. That's illegal in Texas
  • A contractor who says they'll negotiate your claim for you. Only licensed public adjusters and attorneys can represent you
  • Pressure to sign a contract on the spot, or to pay in full up front

FAQ

Common questions

Can a roofer handle my insurance claim for me?

No. In Texas, a contractor can't act as your public adjuster or negotiate your claim. A good roofer can document the damage and meet your adjuster to point out what they found, but you file the claim and make the decisions.

Do I have to pay my deductible?

Yes. Texas law requires homeowners to pay their insurance deductible, and it's illegal for a contractor to waive, absorb or rebate it.

Where can I get official information about claims in Texas?

The Texas Department of Insurance (tdi.texas.gov) has consumer guides on storm claims, choosing a contractor and filing complaints.

Free inspection

Know what your roof needs

Tell us where you are and we'll call within 24 hours to confirm, then be on-site within 2 days. The inspection covers the whole property, not just the roof, and the photo report is free.

(214) 998-1834

Mon–Sun 7am–7pm

No cost, no obligation. We'll only use your number to schedule your inspection.